Alabama Qualifying Income Trust Setup Guide — Qualify a Family Member for Medicaid Before the Next Billing Cycle
For adult children, spouses, and the attorneys, paralegals, and care managers who help them — before another $8,334–$8,787 month of private-pay care goes by.
An Alabama Qualifying Income Trust (also called a Miller Trust or Qualified Income Trust) is an irrevocable trust used to qualify a Medicaid applicant whose monthly income exceeds the Alabama long-term-care income cap of $2,982 per month (CMS January 2026 figures). The trust must be drafted, signed, and funded in the same calendar month using the official Alabama Medicaid template (Ala. Admin. Code r. 560-X-25-.10 (300% of SSI income limit for institutional and waiver Medicaid); Alabama Medicaid Agency Form 262 / Handout #11 (Qualifying Income Trust packet)). Medicaid eligibility can't start before the month the trust is funded (the trust can't be back-dated), and every month of delay is another month of full private-pay nursing-home cost ($8,334–$8,787/mo in Alabama). This guide is the step-by-step operational walkthrough most families need: $97, instant download, money-back if Alabama Medicaid rejects the QIT because of something in the kit.
It applies when the person who needs care has gross monthly income over Alabama's income cap of $2,982, whether you're their child, their spouse, or a professional helping them.
Spouse staying at home?
Only the applicant's own income counts toward this cap, not yours. Separate federal protections keep you from being left without enough to live on: a resource allowance and, when your own income is low, a monthly income allowance. See Medicaid spousal impoverishment protection.
Families often pay an elder-law attorney $1,000–$2,500 for this. The kit lays out every step in order, built around the official Alabama Medicaid template and cited to Alabama Medicaid's own policy. Informational only — not legal advice.
What usually happens
You find the free Alabama Medicaid form, and it looks simple. Then an elder-law attorney quotes $1,000–$2,500 to handle it. So you fill it in yourself, get it signed, and take it to the bank, where the branch has never opened one of these and says no. Meanwhile the month is running out. Coverage can't start before the month the trust is funded, so a month that slips is another $8,334–$8,787 of private-pay care. (Source for the funding rule: Alabama Medicaid, Ala. Admin. Code r. 560-X-25-.10 (300% of SSI income limit for institutional and waiver Medicaid); Alabama Medicaid Agency Form 262 / Handout #11 (Qualifying Income Trust packet).)
The legal document is Alabama Medicaid's own form. What it leaves out is the order of operations: what the bank will ask for before you walk in, and funding the trust before the month closes. In Alabama, the Form 262 packet sets the account up with the applicant's Social Security number, so no separate tax ID is needed. The kit covers the rest: a word-for-word reply for each bank refusal and a printable letter for the branch manager, a funding worksheet built on the 2026 Alabama income cap, and the 8 reasons Alabama Medicaid most often denies these, each cited to Alabama Medicaid's own policy.
You stay in control: you open the account at your own bank, and we never see or touch a dollar of your family's income. Money-back if Alabama Medicaid rejects it, or for any reason within 7 days.
Questions about the kit before you buy? Email support@millertrustguide.com.
- Built on Alabama Medicaid's own .gov template
- Every claim cited to Alabama Medicaid policy
- Last verified against Alabama Medicaid on September 9, 2026
- We never collect your family member's details
- Secure checkout by Stripe
- Money-back if the trust is rejected
What buyers say
A review from a different state — because it's real, and we'd rather show a genuine reader than fill this page with something invented. Retired attorney & CPA is exactly the kind of reader who'd catch it if this guide were sloppy, which is why we lead with it. We only publish verified customers who gave permission — no invented reviews, no stock quotes.
Your Setup Kit turned out to be extremely useful. It got us to the New Jersey QIT template right away, and that was big. We used the Kit to work through the template and the practical questions about how a QIT actually works, and we were able to draft it, get it executed, open a bank account, and submit it with the application in just two or three days. It was an essential need for us, and the Kit helped us accomplish it very quickly.
Not the only one deciding? Send them this page before you dive in.
$8,334–$8,787 a month, Alabama private-pay care
Why this can't wait: until the trust is set up correctly, an over-income applicant can't be approved for Medicaid — so the private-pay bill keeps landing on your family, and your family member's place in care can depend on it. Coverage begins the calendar month the QIT is signed and funded — there is no back-dating — and Alabama private-pay care runs $8,334–$8,787 a month, so every 30 days of delay is another full month of private-pay bills out of pocket.
The 2026 Alabama income cap
- Income cap, single applicant
- $2,982/mo
- Personal needs allowance
- $30/mo
- Alabama private-pay care
- $8,334–8,787/mo
Setting up a Miller Trust in Alabama starts with one number — the income cap. The Alabama 2026 Medicaid long-term-care income limit is $2,982/month for a single applicant. If your family member's countable monthly income exceeds this limit, a properly drafted, signed, and funded QIT diverts the excess and brings countable income below the cap. The applicant's Personal Needs Allowance in Alabama is $30/month. Source: Alabama Medicaid Ala. Admin. Code r. 560-X-25-.10 (300% of SSI income limit for institutional and waiver Medicaid); Alabama Medicaid Agency Form 262 / Handout #11 (Qualifying Income Trust packet) [1].
What's in the Alabama kit
10 operational sections and 3 reference appendices. Here are the six pieces buyers tell other buyers made the difference:
“Isn't the QIT form free from Alabama Medicaid?”
It is — and the kit links you straight to it, at no charge. You're not paying for the form. You're paying for the part that actually trips families up: the same-calendar-month funding rule, the word-for-word bank-refusal script, and the 8 Alabama Medicaid denial traps with the policy citation behind each. The form is a couple of pages; getting it accepted is where a month of coverage gets lost.
If your spouse is the one entering care: this kit covers the Qualified Income Trust — the income side of qualifying — in full. If you're the spouse staying at home (the "community spouse"), the kit also walks you through the trust itself, and Section 9 orients you on the separate resource-allowance rules that protect your home and savings. Those resource rules are fact-specific, so for them you'll likely still want an Alabama elder-law attorney — but the kit's job is to make that a short, cheaper meeting instead of a $1,000–$2,500 one: you walk in with the trust already set up, the resource questions already identified, and the documents already gathered, so you're paying for answers, not for someone to explain the basics to you.
Before you buy
Who this kit isn't for
We'd rather you not buy something you don't need. Skip it if:
- The income is at or under $2,982/month. A Qualifying Income Trust usually isn't needed. Check the number with the free income-cap check.
- The obstacle is savings or property, not income. A Qualifying Income Trust only deals with income. See Medicaid asset protection trusts for the asset side.
- Money or property was given away in the last five years, or other trusts are involved. That needs an Alabama elder-law attorney.
- You want someone to fill it in and file it for you. That's what an attorney does. This kit is for doing it yourself, or for checking someone else's work.
How it works in Alabama
- Confirm income is over the $2,982 cap Gross monthly income, from every source.
- Fill in the official Alabama Medicaid template The state's own form, free from Alabama Medicaid.
- Name a trustee and open the trust account A dedicated bank account titled to the trust.
- Fund it in the same calendar month Eligibility starts that month, never earlier.
Full step-by-step walkthrough →
The funding-month rule
- September Trust not funded Private pay: $8,334–$8,787 for the month.
- October Sign, open, deposit Trust signed, account opened and income deposited, all this month. Eligible from October.
- November onward Deposit every month The income goes into the trust account every month to keep eligibility.
There is no back-dating. Funding in October can't cover September.
What it actually looks like
Sample pages from the kit
Real pages from the Alabama kit PDF. Click any page to enlarge.
-
Cover & key facts
Version, last-reviewed date, the 2026 income cap, and the disclaimer — all on page 1.
View page -
Table of contents
Ten operational sections plus three reference appendices. Every section in the order you'll use it.
View page -
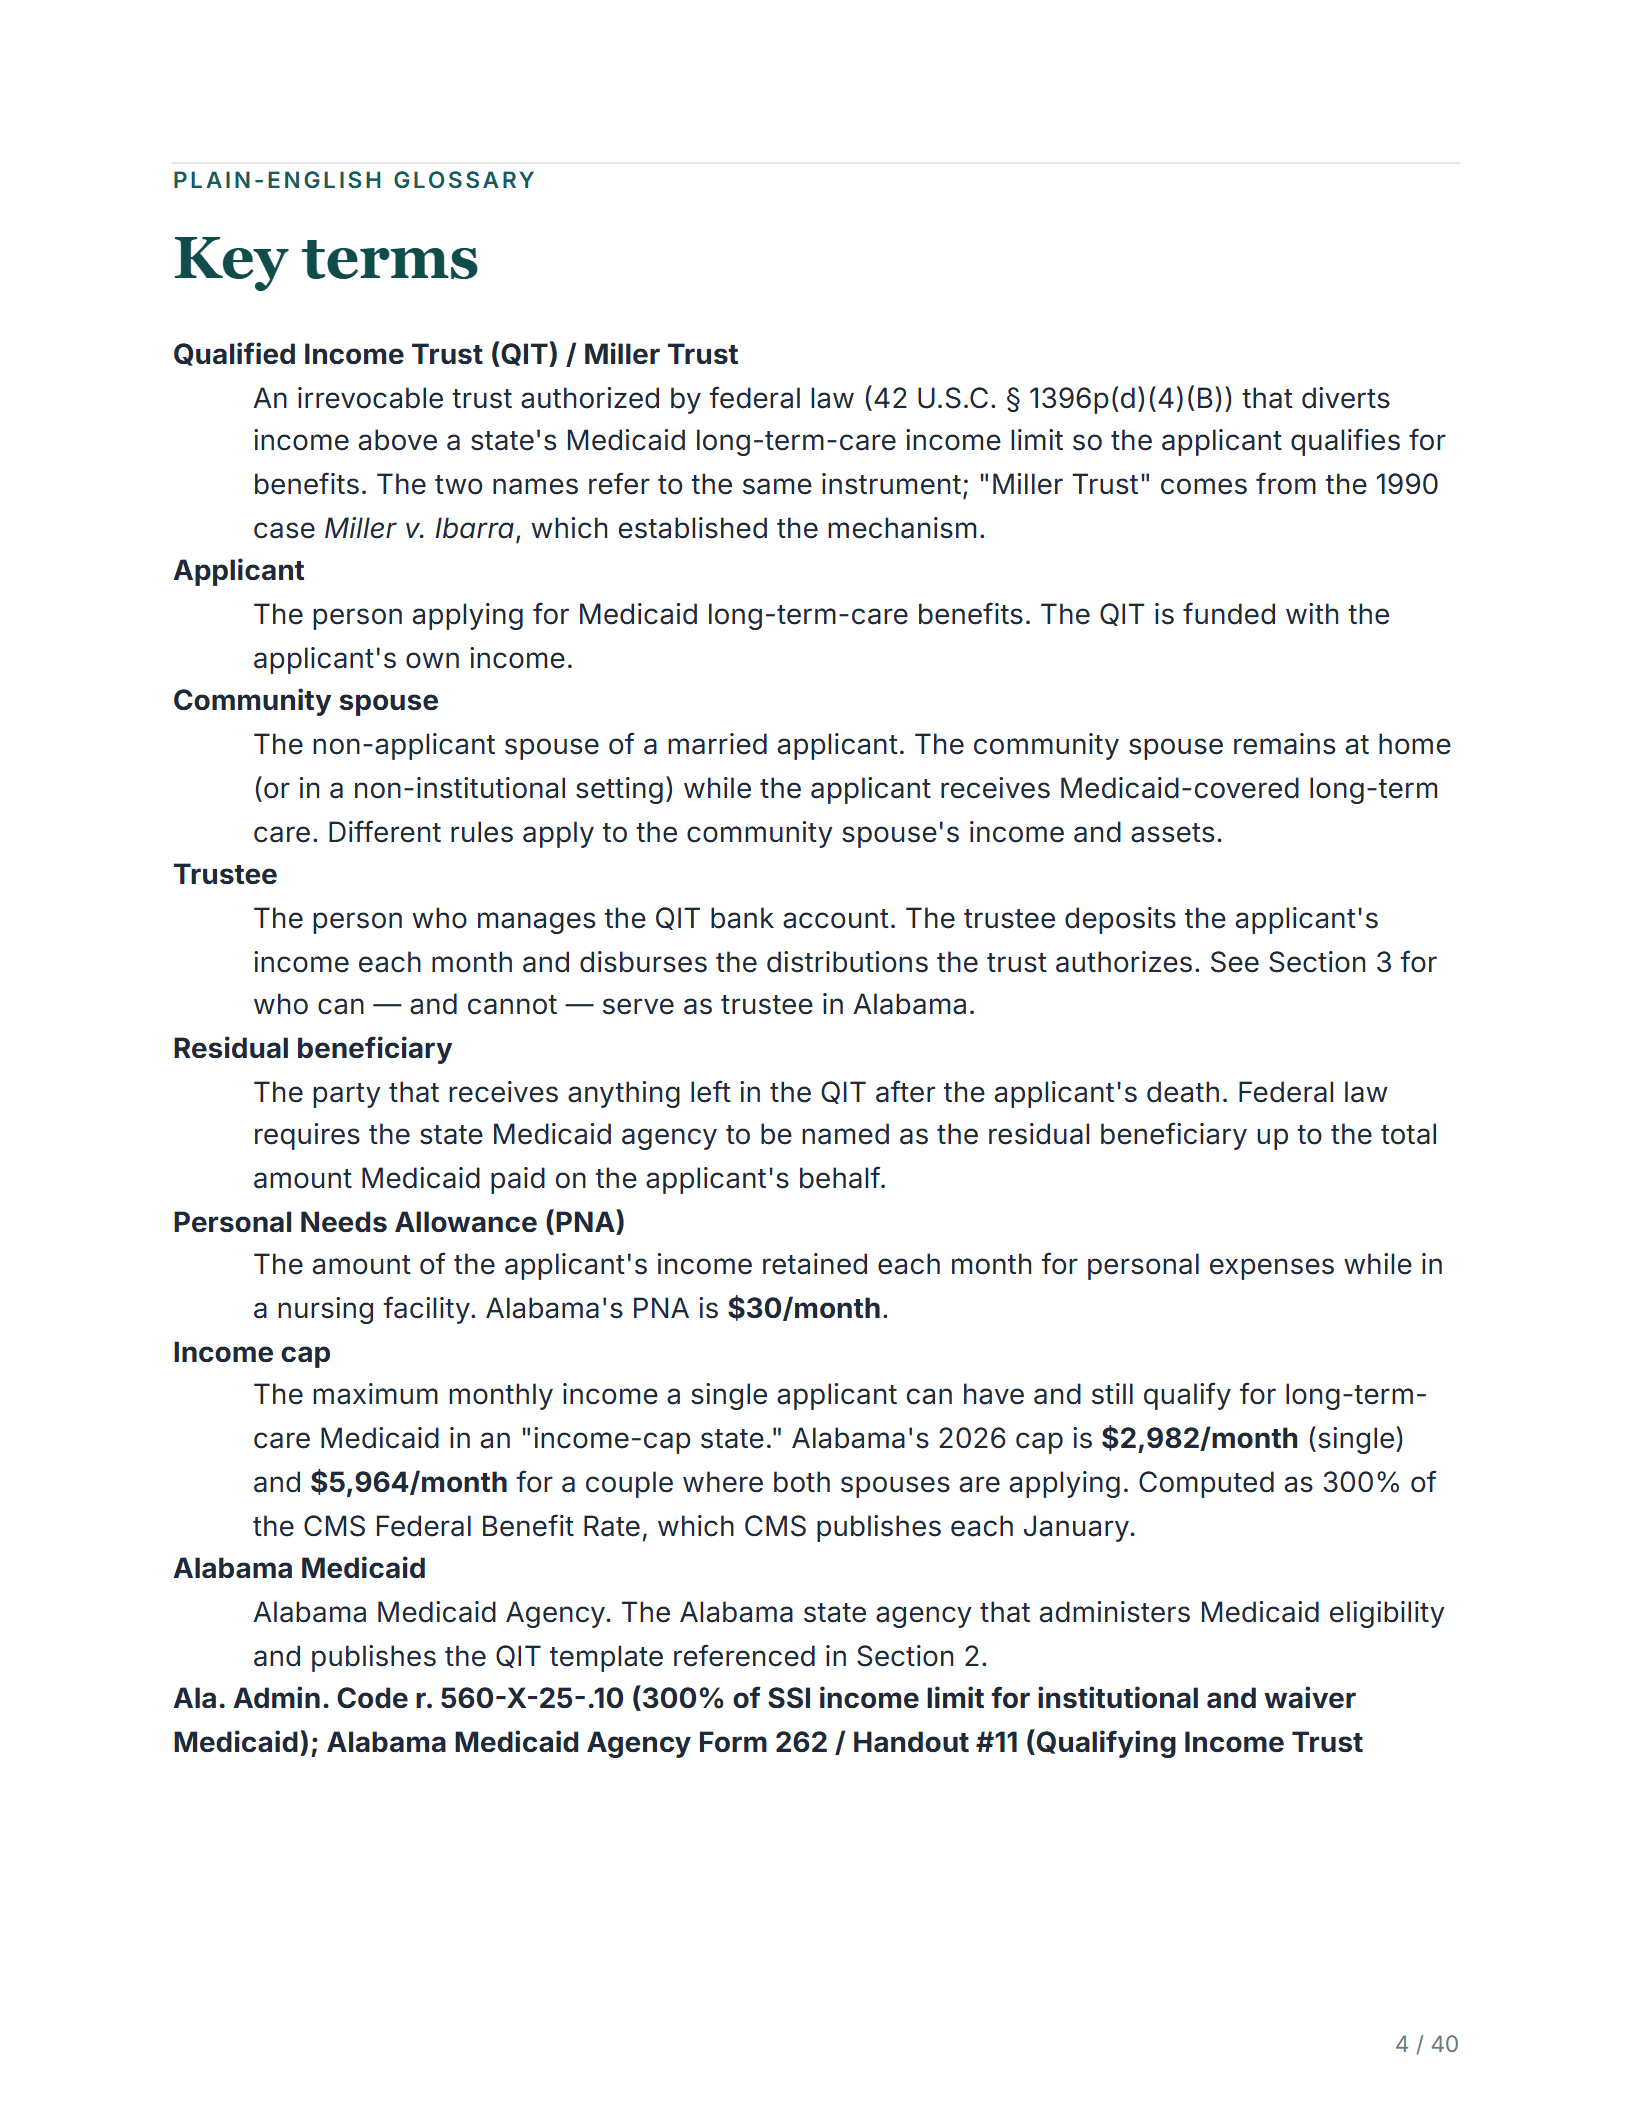
Plain-English glossary
Eleven key terms translated for a non-attorney reader. The vocabulary the rest of the kit assumes.
View page -
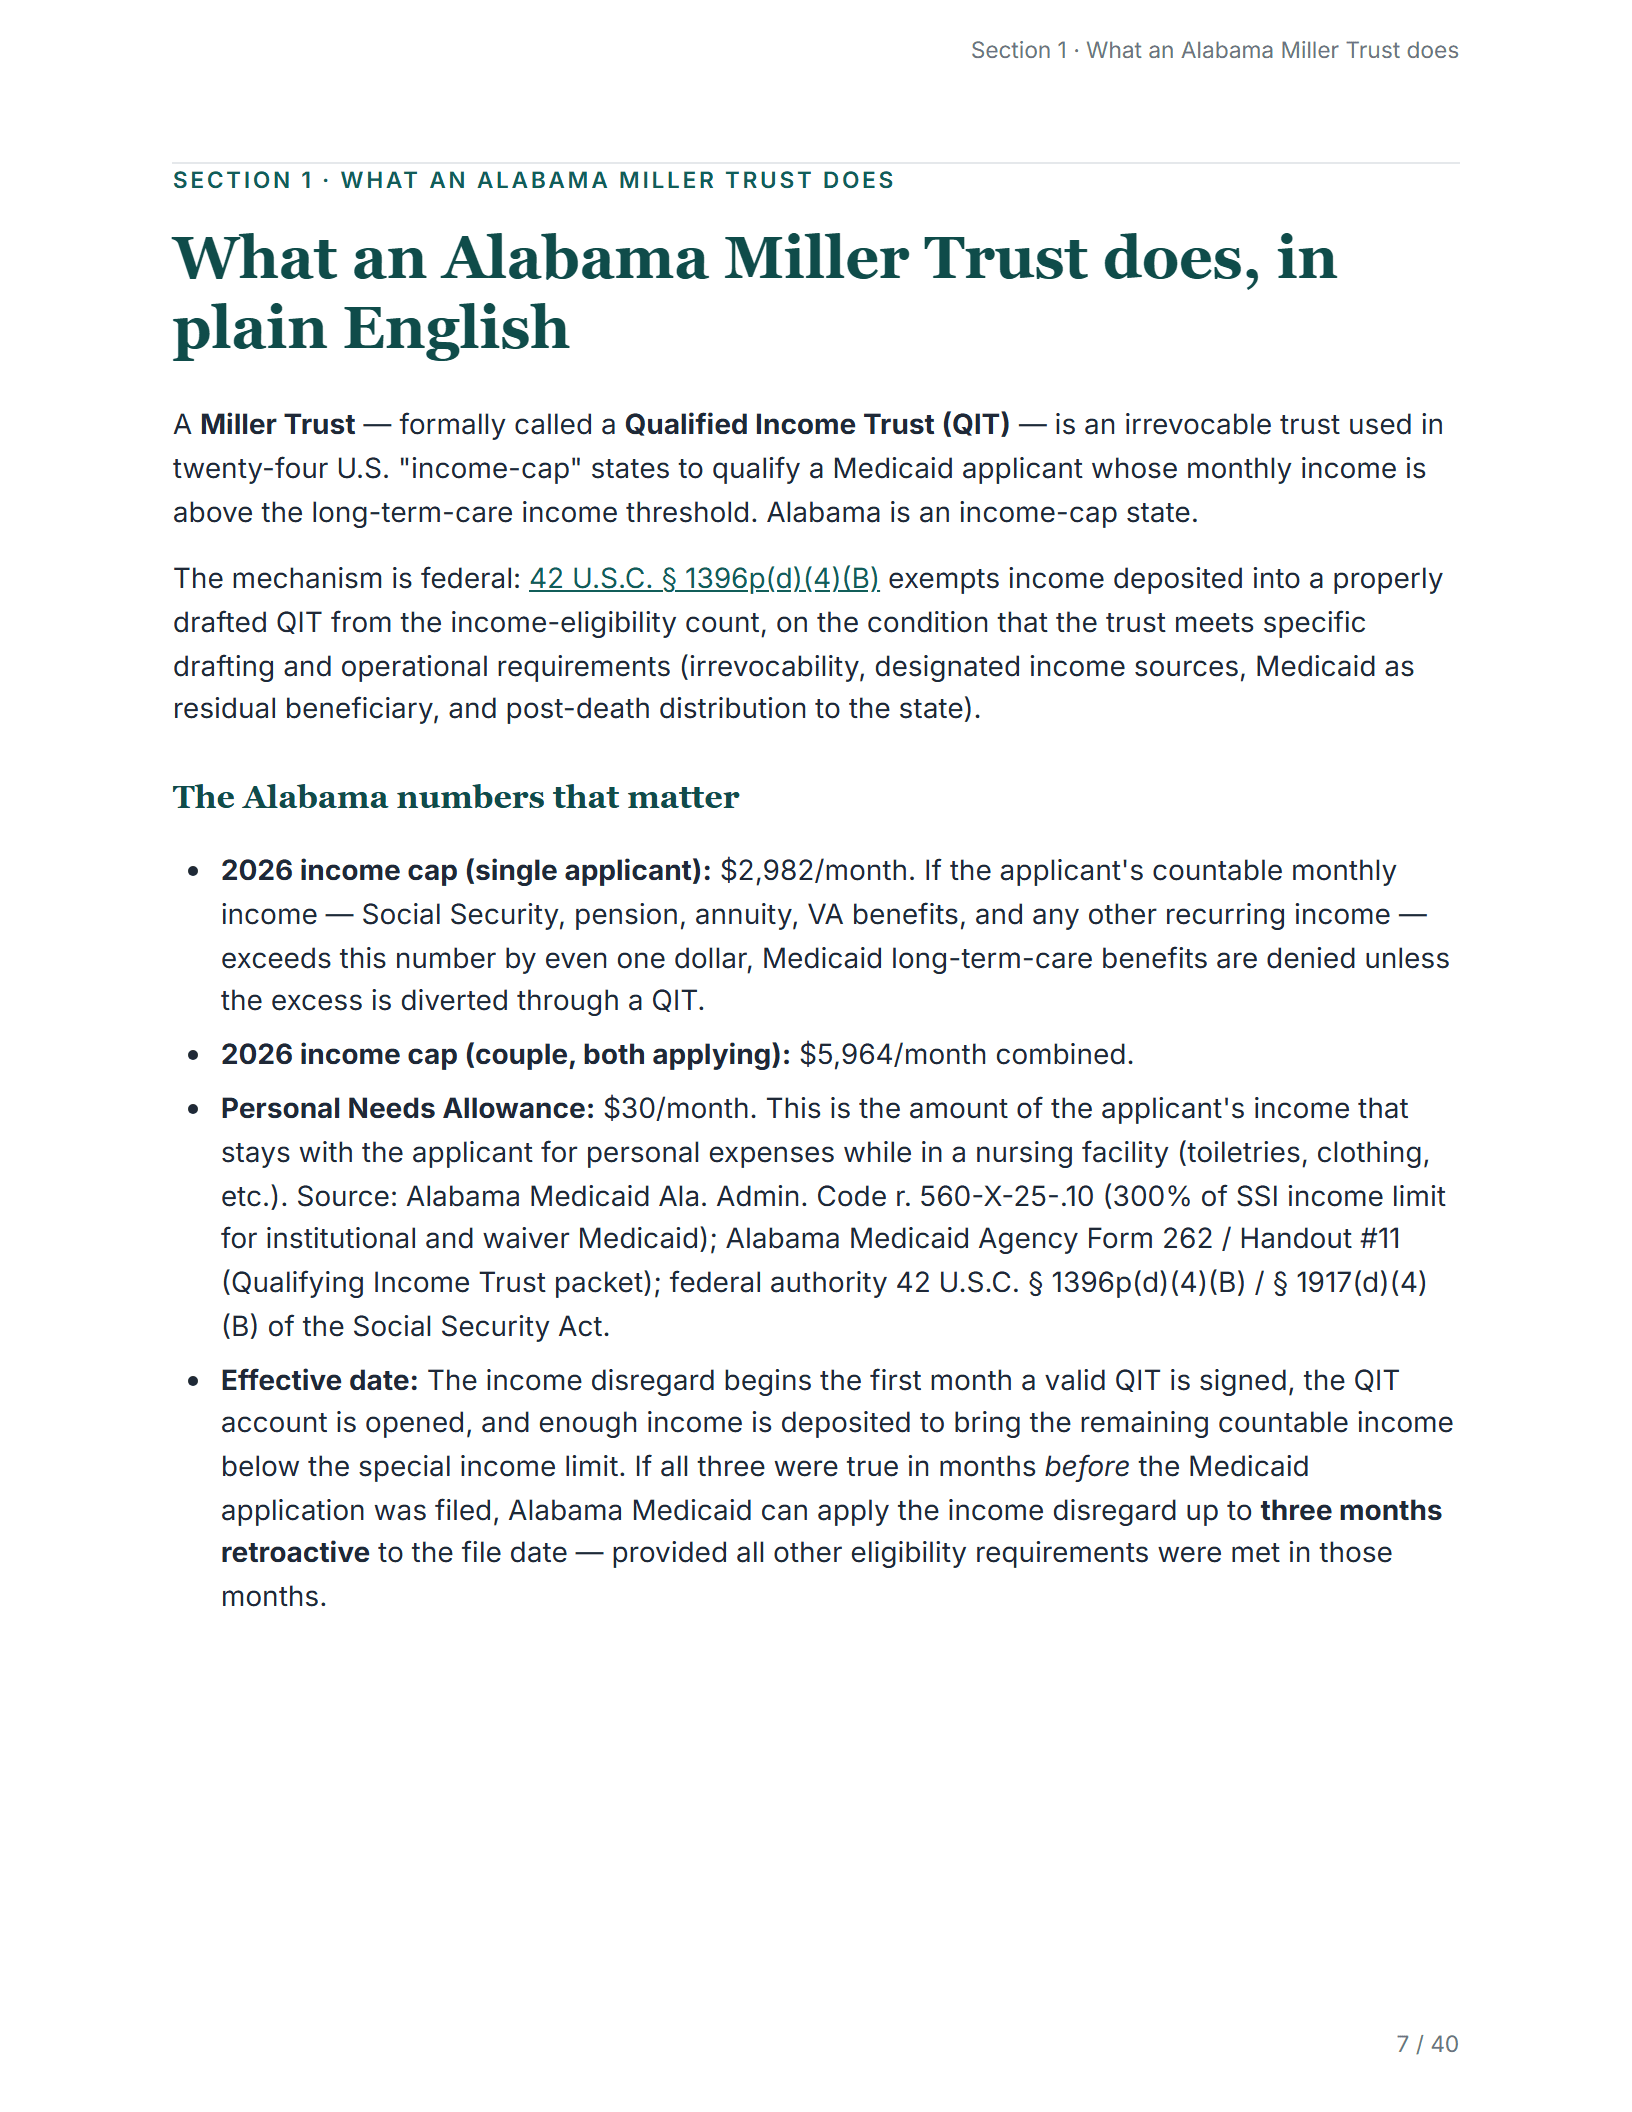
What it does, in plain English
The mechanism explained in plain language, cited to the federal statute, with your state's exact income cap and Personal Needs Allowance built in.
View page -
Citations index
Every operational claim sourced to a primary state-agency, CMS, SSA, or federal-statute citation.
View page
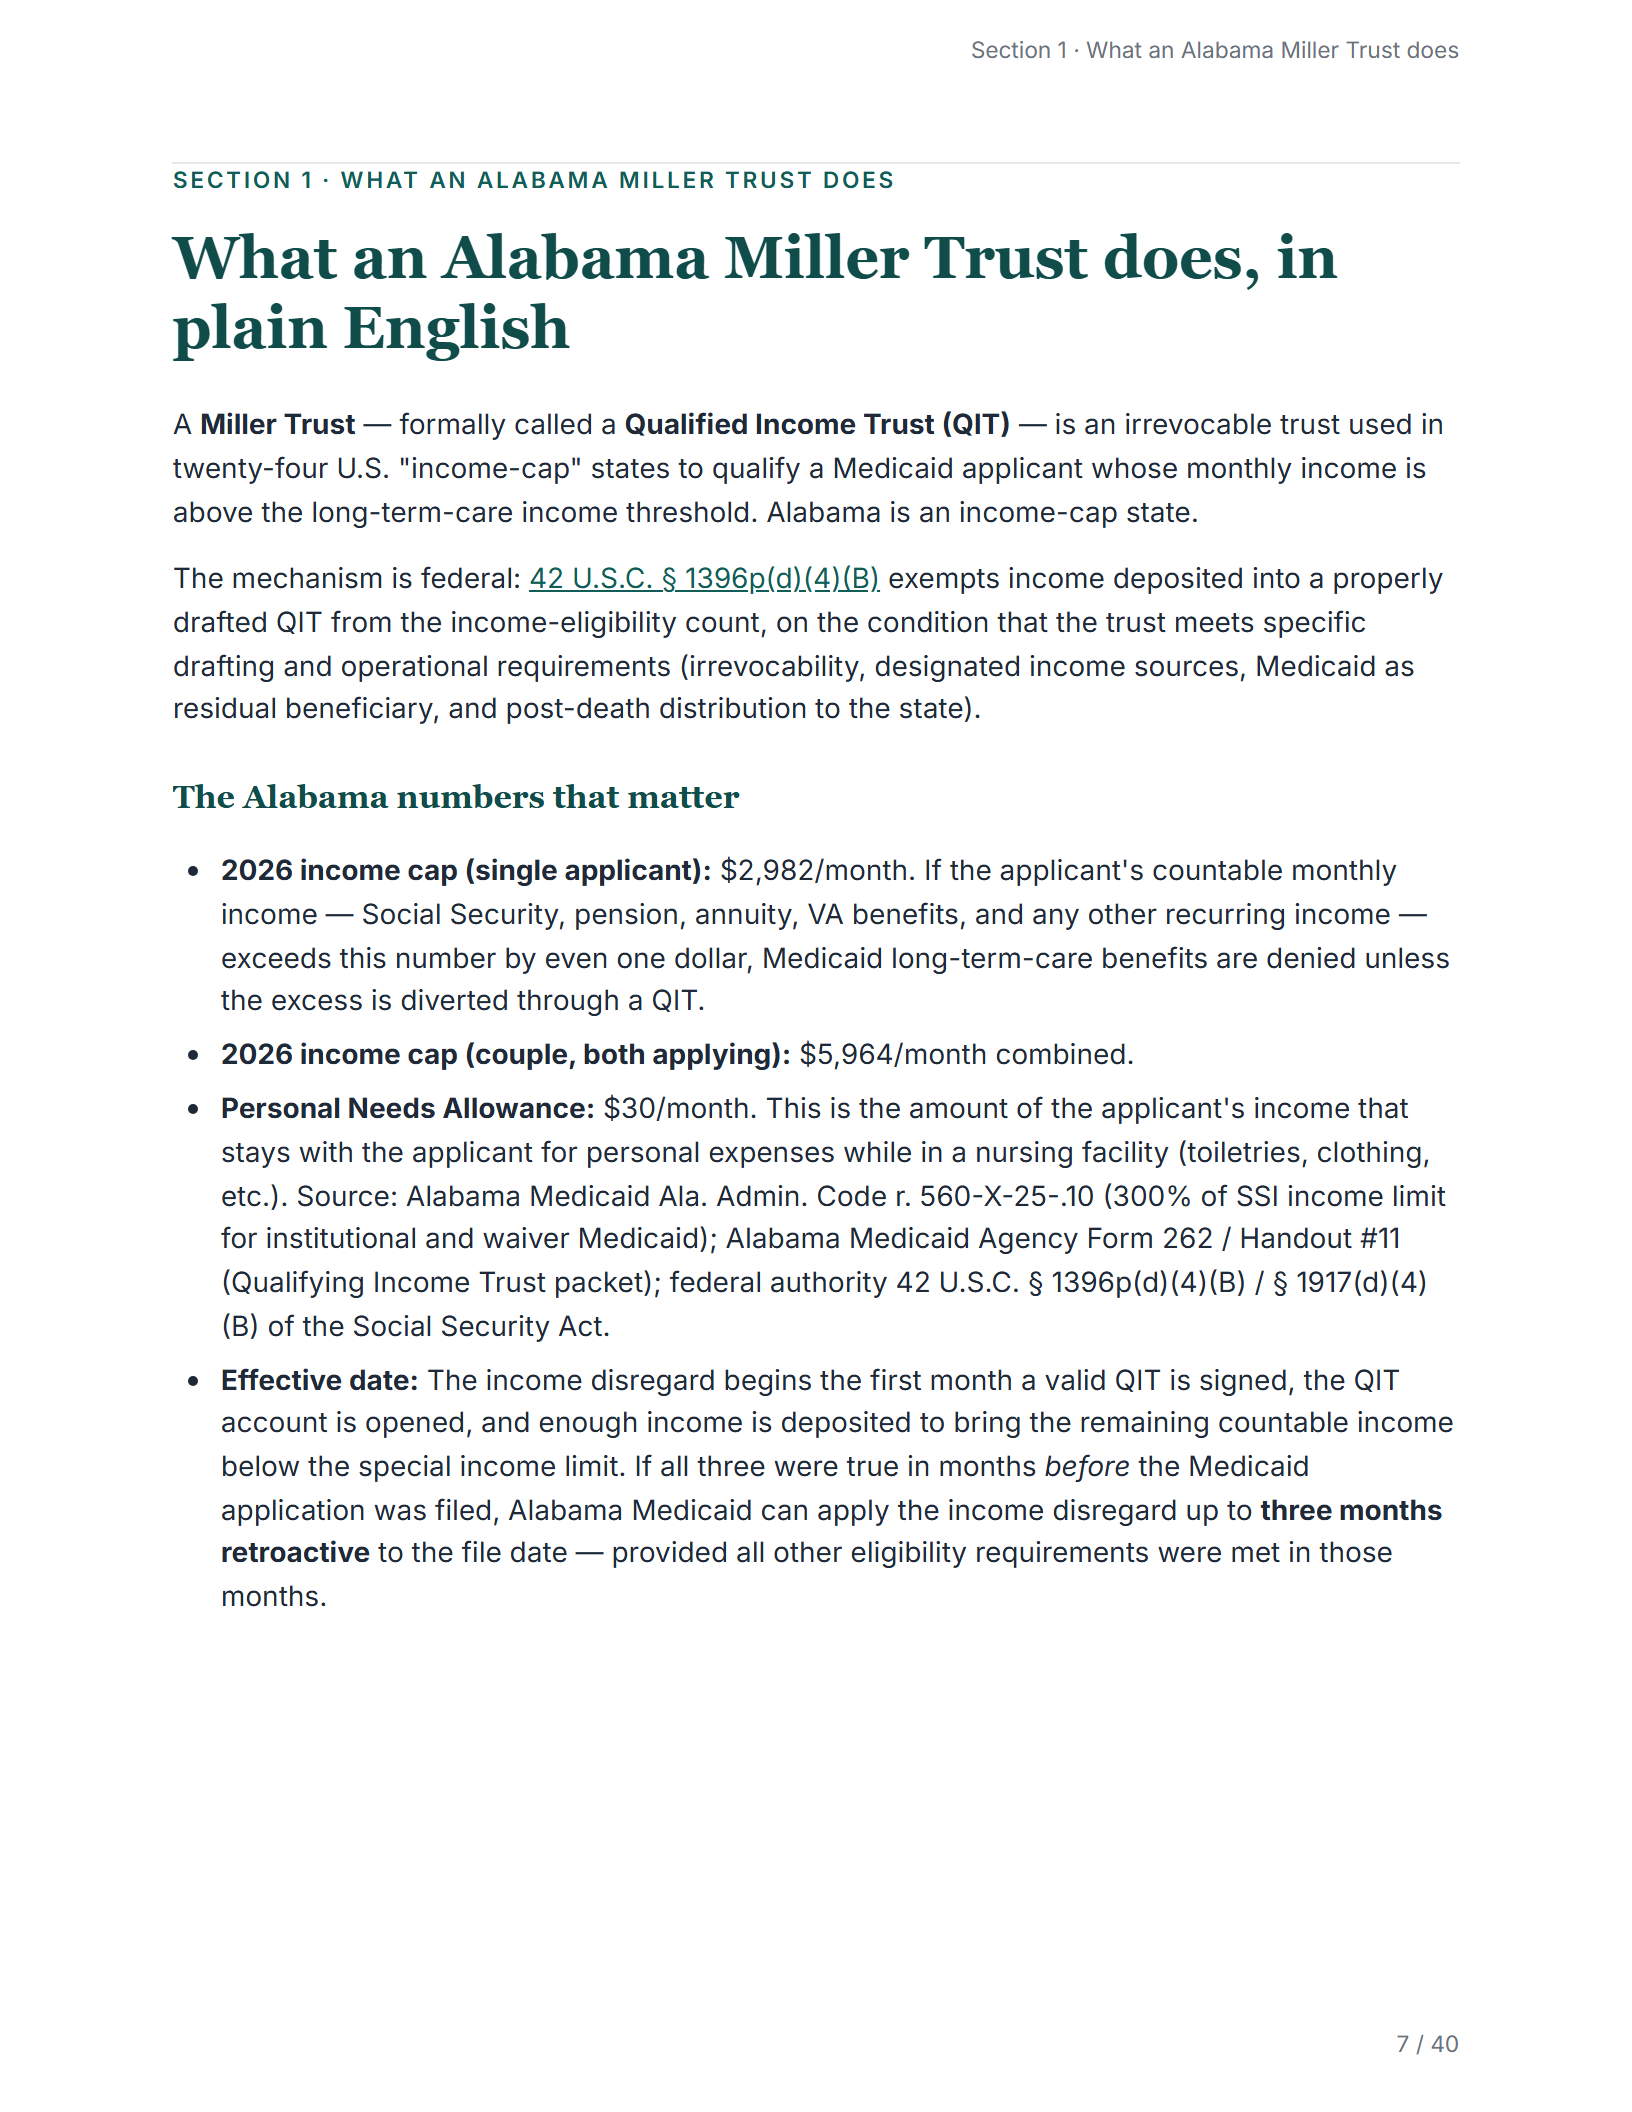
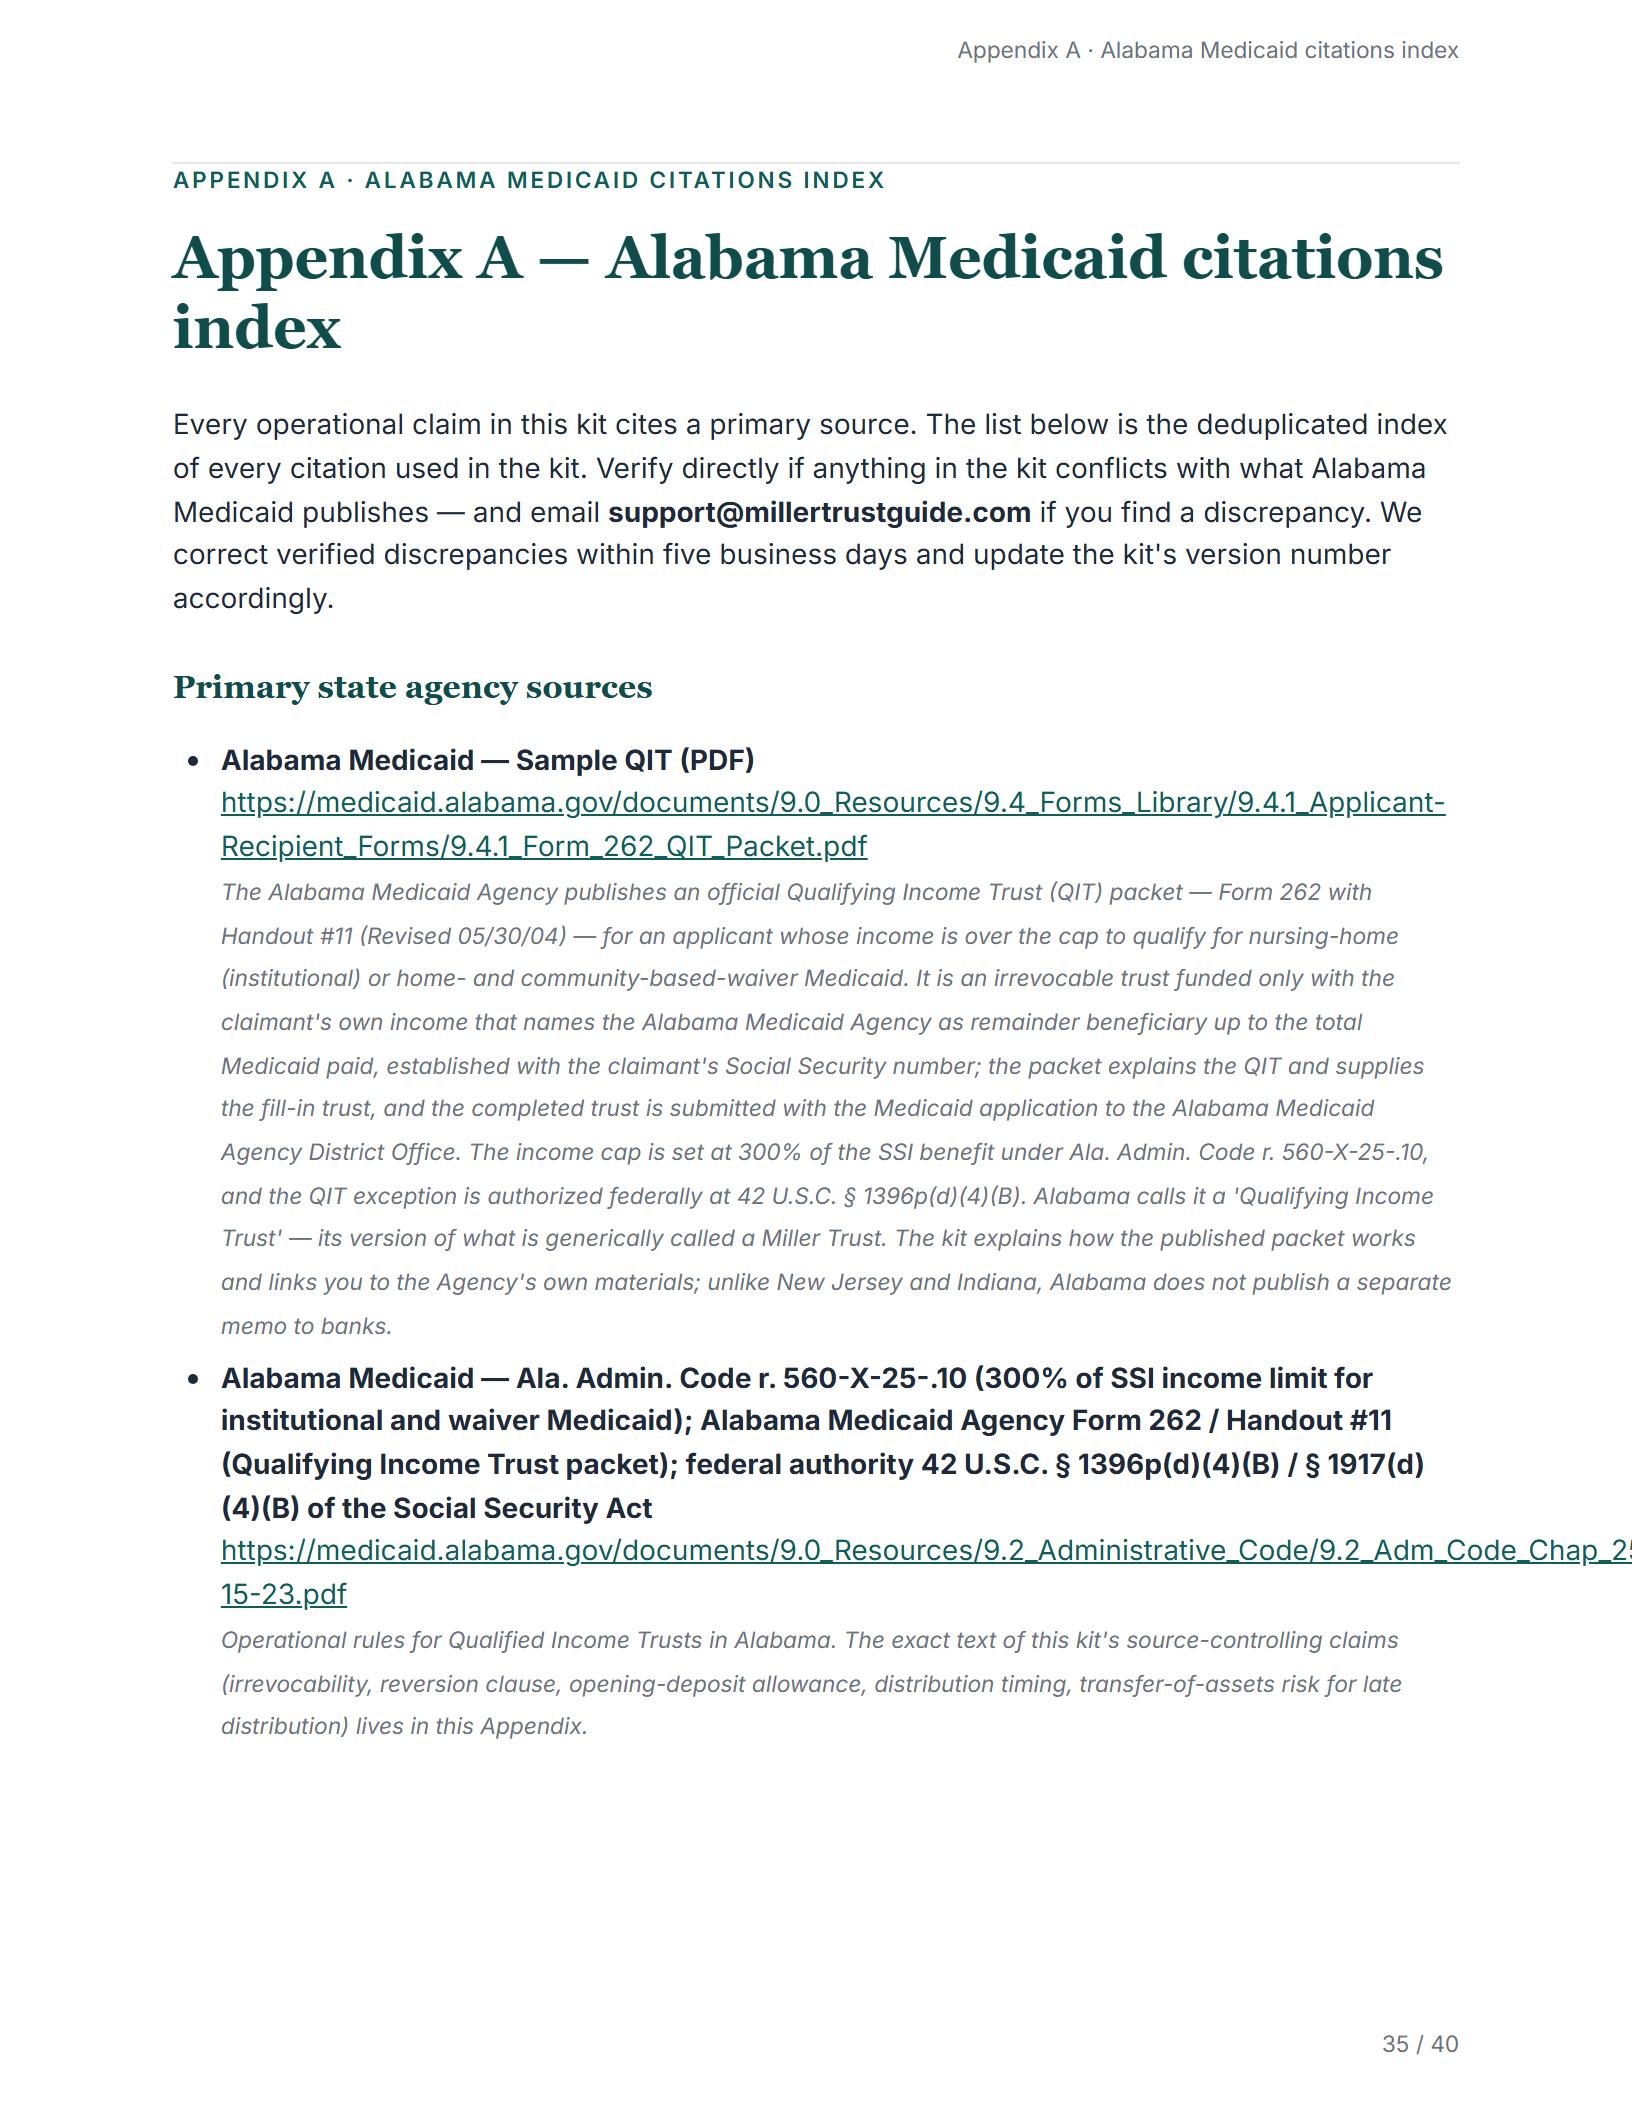
Print-friendly, readable on a phone or tablet, and designed to be taken to the bank. Every operational claim cites a primary state agency or federal source.
How this compares
Yes — Alabama's own QIT form is free (that's the Free state PDF column below). The $97 is for everything the free PDF leaves you to work out alone: the bank step, the funding-month timing, and the denial traps.
| This kit | Elder-law attorney | Free state PDF | Doing nothing | |
|---|---|---|---|---|
| Cost | $97 | $1,000–2,500 | $0 | $0, then $8,334–$8,787/mo private-pay |
| Time to qualified | Same week | 2–6 weeks | If you can decode it alone | Not until you act |
| Bank-refusal script | Yes | Sometimes | No | n/a |
| State agency citations | Yes | n/a | n/a | n/a |
| Updated for 2026 income cap | Yes | Yes | If Alabama has updated PDF | n/a |
| "What to say to family" script | Yes | No | No | n/a |
| Delivery time | Instant download | After consult + retainer | Instant | n/a |
Attorney costs reflect typical Alabama elder-law retainers for a Miller Trust setup. Private-pay nursing-home figures reflect recent Alabama market averages.
The bank step
The bank refusal nobody warns you about
You walk into your branch with the signed trust. The teller calls a manager. The manager has never seen one. They ask for an EIN. They tell you to come back with an attorney. You drive home with an empty trust account and a Medicaid clock ticking.
This is the single most common reason Alabama families lose a month of benefits, and it has nothing to do with the trust itself — it is a bank-procedure problem. The kit's bank section gives you the exact language to cite at the counter, the Alabama Medicaid policy reference to read aloud, and a printable resolution letter you can hand to the branch manager so they can escalate inside their own bank instead of sending you away.
Refusals the kit walks you through:
- Branch asks for a tax ID (EIN) for the trust.
- Branch is unsure how to title the account.
- Branch is unsure what kind of account this is.
- Branch has never opened a Qualifying Income Trust account.
Each refusal has a corresponding response in the kit, with the Alabama Medicaid citation behind it.
The thing that saves a second trip: bring the printed Alabama Medicaid policy page to the counter — not just the signed trust. A teller who can read the rule in black and white escalates in minutes; one who only has your word for it sends you home. The kit tells you exactly which page to print and hand across.
If Alabama Medicaid rejects the trust, you pay nothing.
If the denial is because of something in the kit, email the agency's stated denial reason to support@millertrustguide.com and we refund the full purchase price within one business day. Report it within 30 days of purchase if you can. If Alabama Medicaid hasn't decided by then, email us anyway: the guarantee still applies once you have the denial. No phone tag, no forms, no fight. Changed your mind for any other reason? You have 7 days, no questions asked. We'd rather lose the sale than make this harder on a family already dealing with enough. Full refund policy.
Avoid these
The 8 most common Alabama denial reasons
Every denial reason below cites Alabama Medicaid policy. The full kit explains each one in context and the order in which to verify them before submitting the Medicaid application.
A resource (not income) is placed in the trust
The trust is not irrevocable
Missing or altered State-of-Alabama payback clause
A diverted income check is not deposited in its entirety
The trust is not funded in the correct month
The claimant is named as trustee
Funds are commingled or the account is not a dedicated QIT account
The trust is not properly executed or notarized
Before you go to the Alabama bank
Most wasted trips are a bank-procedure problem, not a trust problem. This free one-pager has the questions to ask on the phone before you drive to a branch — emailed now. We'll also send 4 short follow-ups over the next 10 days (what the bank will ask, why denials are paperwork not eligibility, what other buyers found, when to call an attorney) — then we stop. No ongoing newsletter.
The author
Who's behind this
I'm James Whitfield. I read every Alabama Medicaid policy section on these trusts and tied every step in this kit to the section it comes from, so you can check any of it yourself. I'm a researcher, not an attorney. For advice on your own situation, an Alabama-licensed attorney is the right call.
Questions
Frequently asked questions
Is the Alabama Qualifying Income Trust Kit legal advice?
What does the kit include?
Do you provide the trust template itself?
Who has to set up a Qualifying Income Trust in Alabama?
Does an Alabama Qualifying Income Trust need an EIN?
How much of my income goes into the trust?
Does my entire Social Security check (or other income source) have to go into the Alabama QIT?
Is my income counted before or after the Medicare Part B premium when Alabama checks the $2,982 income cap?
What is the official order of monthly payments out of an Alabama QIT?
When does coverage begin?
What if my bank refuses to open the trust account?
Can I be my own trustee in Alabama?
What happens to the trust after the person on Medicaid passes away?
Do you offer a refund?
Will you talk to me on the phone about my situation?
Will Alabama Medicaid accept a Qualifying Income Trust I fill in myself?
Which banks will open a Qualified Income Trust (QIT) bank account in Alabama?
Can you set up an Alabama Miller Trust without a lawyer?
Can an attorney, paralegal, or care manager use this kit for a client?
Do I need a Miller Trust in Alabama?
What if Alabama Medicaid changes the form or the income cap after I buy?
Ready to start?
$97 for the kit, $129 with the Trustee Ledger, or $49 for the ledger alone. One time. Instant download. Money-back if Alabama Medicaid rejects your QIT because of something in the kit, or for any other reason within 7 days.
No waiting room, no six-week retainer. The steps can be done in a few days. The usual holdup is the bank, and the kit covers what to say at the branch.
See sample pages from the Trustee Ledger
One last step — confirm below and it's instant from there.
Your download link will be emailed to .
Secure checkout by Stripe · Instant download · Money-back guarantee
One-time charge, no subscription. It shows on your card statement as MILLERTRUSTGUIDE.COM.
Already bought? Get your download link
One-time purchase; nothing else is offered after checkout. Any option can be refunded within 7 days for any reason, and if Alabama Medicaid rejects the trust because of something in the kit, you get a full refund of what you paid.
Want them to see the whole case? Send them what you just read.
Not ready to buy yet?
Free 5-email series: the funding-month rule, what really happens at the Alabama bank, why most denials are paperwork not eligibility, who manages the trust each month, and the one honest sign it's time to call an attorney instead. Then we stop. No ongoing newsletter, no sales list.
Keep reading
Step-by-step Alabama guides
New to this? What Is a Miller Trust? covers the plain-English basics — what it is, why states use different names for it, and how it differs from a Medicaid Asset Protection Trust. Below are the free operational walkthroughs that go deeper on the questions Alabama families ask most.
Free operational walkthroughs
- How to Set Up a Qualifying Income Trust in Alabama: Step by Step
- How Long Does It Take to Set Up a Qualifying Income Trust in Alabama?
- How Much Does It Cost to Set Up a Qualifying Income Trust in Alabama?
- Do You Need a Lawyer to Set Up a Qualifying Income Trust in Alabama?
- How Much Does a Nursing Home Cost in Alabama?
- What to Say at the Bank When Opening a Qualifying Income Trust Account in Alabama
- Who Can Be the Trustee of a Qualifying Income Trust in Alabama?
- What Can a Qualifying Income Trust Pay For in Alabama?
- Do You Need an EIN for a Qualifying Income Trust in Alabama?
- What Happens to a Qualifying Income Trust When the Beneficiary Dies in Alabama?
Primary sources
State agency sources
Last verified against Alabama Medicaid on September 9, 2026. Email support@millertrustguide.com if anything below conflicts with what Alabama Medicaid currently publishes — we correct verified discrepancies within five business days.
Every claim here cites a primary Alabama Medicaid or federal document — see them
Primary state agency sources
- Official template: Alabama Medicaid — Ala. Admin. Code r. 560-X-25-.10 (300% of SSI income limit for institutional and waiver Medicaid, incl. the post-eligibility deduction order at .10(4) and gross-income counting incorporated by reference to 20 C.F.R. Part 416 Subpart K) and r. 560-X-25-.16(6) (spousal-impoverishment deduction order); Alabama Medicaid Agency Form 262 / Handout #11 (Qualifying Income Trust packet); federal authority 42 U.S.C. § 1396p(d)(4)(B) / § 1917(d)(4)(B) of the Social Security Act . The Alabama Medicaid Agency publishes an official Qualifying Income Trust (QIT) packet — Form 262 with Handout #11 (Revised 05/30/04) — for an applicant whose income is over the cap to qualify for nursing-home (institutional) or home- and community-based-waiver Medicaid. It is an irrevocable trust funded only with the claimant's own income that names the Alabama Medicaid Agency as remainder beneficiary up to the total Medicaid paid, established with the claimant's Social Security number; the packet explains the QIT and supplies the fill-in trust, and the completed trust is submitted with the Medicaid application to the Alabama Medicaid Agency District Office. The income cap is set at 300% of the SSI benefit under Ala. Admin. Code r. 560-X-25-.10, and the QIT exception is authorized federally at 42 U.S.C. § 1396p(d)(4)(B). Alabama calls it a 'Qualifying Income Trust' — its version of what is generically called a Miller Trust. The kit explains how the published packet works and links you to the Agency's own materials; unlike New Jersey and Indiana, Alabama does not publish a separate memo to banks.
- [1] Policy manual: Alabama Medicaid policy manual (section Ala. Admin. Code r. 560-X-25-.10 (300% of SSI income limit for institutional and waiver Medicaid, incl. the post-eligibility deduction order at .10(4) and gross-income counting incorporated by reference to 20 C.F.R. Part 416 Subpart K) and r. 560-X-25-.16(6) (spousal-impoverishment deduction order); Alabama Medicaid Agency Form 262 / Handout #11 (Qualifying Income Trust packet); federal authority 42 U.S.C. § 1396p(d)(4)(B) / § 1917(d)(4)(B) of the Social Security Act).
- 2026 Medicaid Income Limits sheet (Form 207): Alabama Medicaid — 2026 Medicaid Income Limits sheet (Form 207) . The Alabama Medicaid Agency's official 2026 income and resource limits — the $2,982/month income cap and $2,000 resource limit apply to the Nursing Home (institutional) program and to the Elderly & Disabled, Independent Living, Intellectual Disabilities, and Technology Assisted waivers.
- Estate Recovery FAQ: Alabama Medicaid — Estate Recovery FAQ . The Agency's estate-recovery Q&A; explains that funds remaining in a Medicaid Qualifying Income Trust are owed back to the Alabama Medicaid Agency, and how the Estate Recovery Unit handles repayment.
- Applicant / Recipient Forms Library: Alabama Medicaid — Applicant / Recipient Forms Library . The Alabama Medicaid Agency forms library page where Form 262 (the QIT packet) is listed for download.
- Estate Recovery (Agency page): Alabama Medicaid — Estate Recovery (Agency page) . The Alabama Medicaid Agency Estate Recovery Unit page — the program function that collects the QIT remainder on the beneficiary's death.
Federal sources
- 42 U.S.C. § 1396p(d)(4)(B) — federal Medicaid statute authorizing QITs. https://www.law.cornell.edu/uscode/text/42/1396p
- CMS — 2026 SSI and Spousal Impoverishment Standards. https://www.medicaid.gov/federal-policy-guidance/downloads/cib12092025.pdf . Source for the 2026 Federal Benefit Rate and the 300% cap derivation used in the Alabama income-cap figure.
- SSA — 2026 SSI Federal Payment Amounts. https://www.ssa.gov/oact/cola/SSI.html . Verification of the 2026 FBR figure CMS uses to compute the 300% Medicaid long-term-care income cap.